loan programs

Conventional Loans

A conventional loan is mortgage financing that is not insured or guaranteed by a government program. It is the most widely used structure for buying and refinancing homes.

Conventional home loan program at Boss Mortgage

With flexible terms and competitive rates, conventional loans are a great choice for borrowers with strong credit and stable income. Whether buying your first home or upgrading, we provide the tools and support to make it happen.

Program description as published on bossmortgage.com/products (preserved verbatim).

What this financing is

Conventional financing follows the guidelines of the investors who buy these loans rather than a government insurance program. Those guidelines cover how income and assets are documented, how credit is reviewed and how the property is appraised.

Because conventional guidelines cover a wide range of scenarios — primary residences, second homes and investment properties — it is often the first structure worth pricing, even when another program ends up fitting better.

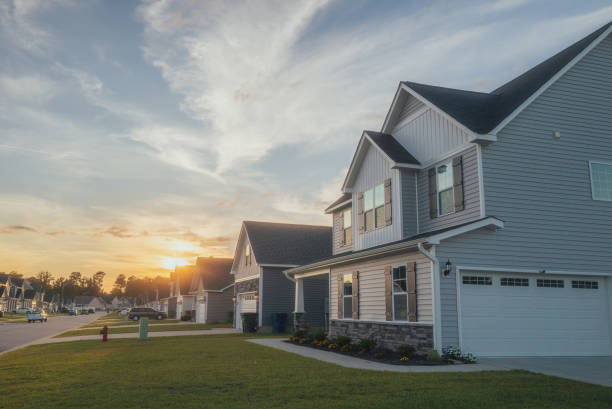
A two-story suburban house with a mown front lawn in afternoon light

Who it may be a fit for

Buyers purchasing a primary residence

Homeowners refinancing an existing mortgage

Borrowers who want to compare mortgage insurance structures

Buyers of a second home

Borrowers moving up from a starter home

Not sure if Conventional Loans fits your situation?

A licensed Boss Mortgage loan originator can look at the details with you and explain what applies to you.

A community event the Boss Mortgage team takes part in

What to think about

Down payment and mortgage insurance work together

How much you put down relative to the value of the home affects whether mortgage insurance applies and how it is structured. Your loan originator can price several scenarios so you can see the difference in the monthly payment.
Documentation matters as much as the numbers

How your income is documented can matter as much as the amount. If you are self-employed or have variable income, mention it early so the file is built correctly from the start.

Occupancy changes the guidelines

Primary residence, second home and investment property are reviewed differently. Be clear about how you plan to use the property.

How the process works

1. Get approved

Connect with a BOSS Mortgage loan originator, review your financing options, and provide the information needed to understand your buying power before you start shopping.

Connect with a BOSS Mortgage loan originator, review your financing options, and provide the information needed to understand your buying power before you start shopping.

Two people talking on the steps of a home, from the Boss Mortgage image libraryTwo people standing on the front porch of a house holding a set of keysA small apartment building with balconies in evening light

Frequently asked questions

What is a conventional loan?

A conventional loan is mortgage financing that is not insured or guaranteed by a government program such as FHA, VA or USDA. It follows the guidelines of the investors who purchase these loans.

Terms, rates and programs are subject to change, and not all customers will qualify.

Does a conventional loan require mortgage insurance?

Mortgage insurance on a conventional loan depends on the amount you put down relative to the value of the home and on current investor guidelines.

Your loan originator can show you how it would apply to the scenario you are considering.

Can a conventional loan be used for a second home or rental property?

Conventional financing is often used for primary residences, and there are also guidelines that address second homes and investment properties. Requirements differ by occupancy type.

If you are buying a rental, ask about investor and DSCR options as well so you can compare structures.

How much do I need for a down payment?

As little as zero with programs like VA, USDA and DPA! The amount you need depends on the loan type. FHA loans may require as little as 3.5%, while Conventional loans often range from 3% to 20%. We’ll work with you to find a solution that fits your budget.

Where can down payment funds come from?

Depending on the program, funds may come from savings, the sale of another asset, retirement accounts, gifts or down payment assistance. Each source has its own documentation requirements.

Tell your loan originator early where the funds will come from so the paperwork can be prepared correctly.

Are closing costs the same as the down payment?

No. The down payment is applied to the purchase price, while closing costs cover items such as title, recording, prepaid amounts and lender fees.

Your Loan Estimate and Closing Disclosure show these amounts for your specific transaction.

Ready to get started?

Every situation is different. We’ll help you understand your options and what may fit your goals.

This page is general information about mortgage financing and is not a commitment to lend, an offer of credit, or financial or legal advice. Program availability, guidelines and requirements are set by lenders and investors, can change, and depend on your individual circumstances and the property. Talk with a licensed Boss Mortgage loan originator about what applies to you.

Boss Mortgage LLC NMLS #2547821. See the Licensing page for state licensing information. Additional disclosures appear in the footer of every page.