Who may qualify
VA loan eligibility generally applies to eligible veterans, active-duty service members, and certain surviving spouses. A Certificate of Eligibility confirms whether the VA has established entitlement for the borrower.
A VA loan is mortgage financing guaranteed by the Department of Veterans Affairs and available to eligible veterans, active-duty service members and certain surviving spouses.
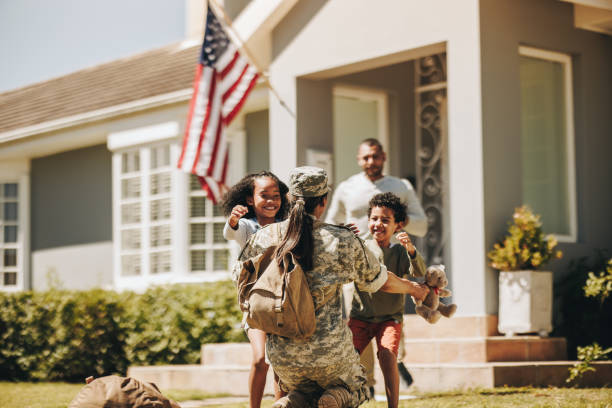
We proudly offer VA loans to honor the service of our military members and veterans. With a VA loan, eligible borrowers can access benefits like no down payment requirement. Whether you’re a veteran, active-duty service member, or a surviving spouse, our dedicated team is here to guide you through the VA loan process with personalized support and expertise. Let us help you achieve your homeownership goals while you focus on what matters most.
Program description as published on bossmortgage.com/products (preserved verbatim).Eligibility for VA financing is established by the Department of Veterans Affairs through a Certificate of Eligibility. The loan itself is made by a lender, and the VA guarantee is what makes the program's terms possible.
Boss Mortgage is not affiliated with, and its products have not been approved or endorsed by, any government agencies. Our team helps eligible borrowers gather documentation and understand what the program involves.
Eligible veterans and active-duty service members looking to finance a primary residence.
Certain surviving spouses who meet VA eligibility requirements.
Eligible borrowers who have used their VA benefit before and may be able to use it again, depending on entitlement and current VA guidelines.
Service members relocating to a new duty station who need financing for a home they will occupy.
A licensed Boss Mortgage loan originator can look at the details with you and explain what applies to you.
VA loan eligibility generally applies to eligible veterans, active-duty service members, and certain surviving spouses. A Certificate of Eligibility confirms whether the VA has established entitlement for the borrower.
Many eligible borrowers use VA financing more than once over a lifetime, depending on entitlement and current VA guidelines.
VA financing is intended for homes the borrower will occupy. Ask about how that applies if you are relocating.
Homes for Heroes is a separate program Boss Mortgage participates in, not part of the VA loan itself. See the existing Homes for Heroes information for its terms and disclosures.
Connect with a BOSS Mortgage loan originator, review your financing options, and provide the information needed to understand your buying power before you start shopping.
Connect with a BOSS Mortgage loan originator, review your financing options, and provide the information needed to understand your buying power before you start shopping.
Shop with a clear budget in mind. When you find the right property, your loan originator can help you understand the financing details that apply to that home and your offer.
Once you are under contract, the BOSS Mortgage team helps keep the loan moving through documentation, underwriting, and closing so you can get the keys and move forward.
VA financing is available to eligible veterans, active-duty service members and certain surviving spouses. Eligibility is established by the Department of Veterans Affairs through a Certificate of Eligibility.
Boss Mortgage is not affiliated with any government agency. Our team can help you understand the documentation involved.
Many eligible borrowers use VA financing more than once over a lifetime, depending on entitlement and current VA guidelines.
A loan originator can review your Certificate of Eligibility and explain what is available to you.
No. A VA loan is a mortgage program. Homes for Heroes is a separate program Boss Mortgage participates in that can provide savings for qualifying heroes.
The two can sometimes apply to the same transaction. Details, eligibility and disclosures for Homes for Heroes are published on the existing Boss Mortgage pages.
As little as zero with programs like VA, USDA and DPA! The amount you need depends on the loan type. FHA loans may require as little as 3.5%, while Conventional loans often range from 3% to 20%. We’ll work with you to find a solution that fits your budget.
Depending on the program, funds may come from savings, the sale of another asset, retirement accounts, gifts or down payment assistance. Each source has its own documentation requirements.
Tell your loan originator early where the funds will come from so the paperwork can be prepared correctly.
No. The down payment is applied to the purchase price, while closing costs cover items such as title, recording, prepaid amounts and lender fees.
Your Loan Estimate and Closing Disclosure show these amounts for your specific transaction.
Boss Mortgage participates in the Homes for Heroes program. See the program details and disclosures as published by Boss Mortgage.
Learn more →
Learn how conventional mortgage financing works, who it may suit and how to talk it through with a licensed Boss Mortgage loan originator.
Learn more →
How FHA mortgage financing works, the scenarios it often suits and how to review it with a licensed Boss Mortgage loan originator.
Learn more →
Refinancing and home equity line of credit options from Boss Mortgage, and how to decide which one fits your goal.
Learn more →Every situation is different. We’ll help you understand your options and what may fit your goals.
This page is general information about mortgage financing and is not a commitment to lend, an offer of credit, or financial or legal advice. Program availability, guidelines and requirements are set by lenders and investors, can change, and depend on your individual circumstances and the property. Talk with a licensed Boss Mortgage loan originator about what applies to you.
Boss Mortgage LLC NMLS #2547821. See the Licensing page for state licensing information. Additional disclosures appear in the footer of every page.